Input VAT recovery on employee expenses in the UAE now has a clear rulebook. The Federal Tax Authority (FTA) issued Decision No. 17 of 2026 on 9 September 2026, and it takes effect on 1 October 2026.
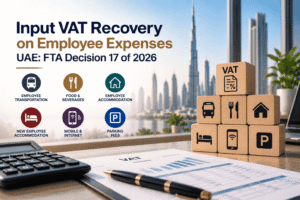
The Decision lists six types of employee expenses and the conditions each must meet. If your business provides staff transport, housing, meals, mobile phones or parking, your VAT treatment may need to change.
This guide explains each case in plain terms, shows where businesses are likely to go wrong, and sets out how to prepare. Tax Gian’s VAT consultants can review your position before the deadline.
What is FTA Decision No. 17 of 2026?
The Decision sets out the cases and conditions under which a taxable person may recover input VAT on goods and services provided free of charge to employees. It applies where there is a contractual obligation or a documented policy to provide them, in line with Article 53(1)(c) of Cabinet Decision No. 52 of 2017 (the VAT Executive Regulation).
Two points matter most:
- Each of the six cases carries its own conditions, and all of them must be met, not just some.
- Recovery is only available in these listed cases. Other free benefits for staff should be reviewed carefully before any input VAT is claimed.
The Six Employee Expenses Covered
1. Employee transportation
Input VAT is recoverable only if all of the following apply:
- The service runs only between the employee’s home and the workplace or client premises, or for purposes directly related to job duties.
- It is not used for the employee’s personal benefit.
- The employee cannot opt for a cash allowance or other compensation instead.
2. Food and beverages
This is the narrowest category. All of these must be true:
- The employee lives in a remote, distant or isolated area.
- There are no suitable food preparation facilities at the residence or workplace, and no nearby restaurants.
- The food is directly linked to the work period or residence period the job requires.
- The employee cannot take a cash allowance instead.
3. Employee accommodation
Staff accommodation is a common area of VAT disputes. Recovery requires that:
- The employee cannot opt for a cash allowance instead.
- The accommodation relates to operational requirements and is not part of the employee’s ordinary benefits or compensation.
- The work requires the employee to live near the workplace, work site or client location.
- It is for the employee alone, not family members or personal use. The exception is where the employee must live permanently near the workplace, so it is their usual residence.
- It is commensurate with job requirements and basic residency needs, without significant recreational or personal features.
4. Accommodation for new employees
- The accommodation is temporary and lasts no longer than 30 days.
- It is commensurate with job requirements and basic residency needs.
5. Mobile phones, airtime, data and home internet
This covers phones, airtime, data packages and internet access from the residence via a modem or router. The conditions are:
- The items are necessary for the employee to perform their duties, including outside normal hours or when working remotely.
- Use is limited to work, and any personal use is incidental and insignificant.
- The employer has a documented internal policy setting out permitted use and the consequences of unauthorised use.
- The employer can demonstrate reasonable monitoring mechanisms and keeps records and justifications where unauthorised use occurs.
5. Parking fees
- The fees are incurred solely for business purposes, such as job duties or business visits.
- There is a documented policy on reimbursement and approvals.
- Payment evidence is retained, such as receipts showing the date, time, amount and tax paid.
Common Mistakes Businesses Should Avoid
Based on the Decision’s wording, these are the areas most likely to draw scrutiny:
- Offering a cash allowance option. For transport, food and accommodation, this alone defeats recovery.
- Treating housing as a standard package. Accommodation that forms part of ordinary compensation does not qualify.
- Having no written policy. Mobile, internet and parking claims depend on documented policies.
- Weak records. Missing tax invoices or receipts make a claim hard to defend in an FTA audit.
- Assuming the Decision covers every staff benefit. It covers six cases only.
How to Prepare before 1 October 2026
- Map every free benefit you provide to employees, and match each to one of the six cases.
- Review employment contracts and allowance structures for cash-in-lieu options.
- Put written policies in place for mobile, internet and parking, with approval and monitoring processes.
- Check your record-keeping so that tax invoices and receipts are complete and retrievable.
- Review past VAT returns for similar claims, and consider whether any corrections are needed.
Frequently asked questions
When does FTA Decision No. 17 of 2026 take effect?
It takes effect on 1 October 2026, following publication in the Official Gazette.
Can my company recover VAT on staff accommodation?
Yes, but only where every condition in the Decision is met. These include no cash-in-lieu option, an operational need, and accommodation that is not part of ordinary staff benefits.
Is VAT on employee meals recoverable?
Only in limited cases, such as staff living in remote or isolated areas with no food facilities or nearby restaurants.
Can I claim input VAT on employee mobile phones?
Yes, if the phones are necessary for the job, personal use is incidental, and you have a documented policy and monitoring in place.
What documents should I keep?
Keep tax invoices, parking receipts showing date, time, amount and tax, written policies, employment contracts and monitoring records.
How Tax Gian can help
Tax Gian is one of the top UAE tax advisory firms. Our VAT consultants can help you:
- Draft compliant internal policies for mobiles, internet and parking
- Review employment and accommodation arrangements against the Decision
- Support VAT return filing and FTA audit preparation
Speak to a Tax Gian VAT expert today. Request a consultation through our contact page, and protect your input VAT claims before the new rules apply.